
QuantOracle MCP server
Commit 13. Nov. 2026Bietet 63 deterministische Finanzrechner und 10 Composite Workflows für autonome Agenten zur Durchführung quantitativer Analysen.
Auch bekannt als QuantOracledev/quantoracle
- Stars
- 14
- Tools
- —
- Downloads, 30 Tage
- —
- Neueste Version
- —
- Letzter Commit
- 13. Nov. 2026
- Lizenz
- MIT
Was ist QuantOracle MCP?
QuantOracle ist ein MCP server. Bietet 63 deterministische Finanzrechner und 10 Composite Workflows für autonome Agenten zur Durchführung quantitativer Analysen.
Zusammenfassung generiert aus dem README des Projekts
Über QuantOracle MCP server
QuantOracle bietet eine Suite aus 63 deterministischen Finanzrechnern und 10 Composite Workflows, die speziell für autonome Finanzagenten entwickelt wurden. Es fungiert als quantitative Computation API, die es Agenten ermöglicht, exakte mathematische Operationen durchzuführen, anstatt sich auf die probabilistische Natur von Large Language Models zu verlassen. Der Service ist über einen MCP server, ein Command Line Interface oder direkte API-Requests zugänglich.
Nutzer können auf die Kernrechner kostenlos zugreifen, mit einem Limit von 1.000 Aufrufen pro IP-Adresse und Tag, ohne einen API-Key oder eine Account-Registrierung zu benötigen. Für fortgeschrittenere Anforderungen bietet die Plattform kostenpflichtige Composite Workflows wie Strategy Backtesting, Hedging-Empfehlungen und Portfolio Rebalancing an. Diese Premium-Features sowie die Live-Data-Tier, die aktuelle Krypto-Volatilität und Funding Rates liefert, werden über x402 Micropayments auf den Base- oder Solana-Netzwerken abgewickelt. Das System ist auf Geschwindigkeit ausgelegt, mit Rechenzeiten oft unter 70ms, und jede Formel ist durch Zitate gegen etablierte Finanzlehrbücher verifiziert.
Was du damit machen kannst
- 1Portfolio-Risikoanalyse durchführenEin Nutzer kann eine umfassende Risikobewertung anfordern, indem er eine Reihe von Renditen bereitstellt.
Geschrieben aus dem README des Projekts. Jeder Use Case wurde gegen ein Zitat daraus geprüft.
Automatisierte Checks
Geluften am 14. Nov. 2026Vollständiger Bericht →Noch nicht verifiziert. Ein Server benötigt einen Score von 80, keine kritischen Befunde und genug Daten für unsere Prüfung. Wie die Checks funktionieren · Was du für mehr Punkte verbessern kannst

- Source Repository verknüpft und erreichbarquantoracledev/quantoracle is public and reachablegithub.com/quantoracledev/quantoracle ↗Bestanden
- Paket nennt dieses Repository als QuelleNicht geprüft
- Build-Provenienz (Sigstore-Attestierung)Nicht geprüft
- Open Source Lizenz (OSI)MITspdx.org/licenses/MIT.html ↗Bestanden
- Commit oder Release im letzten JahrLast commit or release 2026-11-13github.com/quantoracledev/quantoracle ↗Bestanden
- OpenSSF ScorecardNicht geprüft
- Package-Name ähnelt keinem populären PackageNicht geprüft
- Keine kritischen Advisories im Paket oder seinen AbhängigkeitenNicht geprüft
- Keine versteckten Anweisungen an das Modell0 tool descriptions and the README read; no override phrases, credential paths or hidden charactersBestanden
- Destruktive Tools sind markiertNicht geprüft
- Remote-Endpoint beantwortet den MCP-HandshakeNicht geprüft
README
Auf GitHub ansehenTry it without writing code
12 free interactive calculators backed by the same API are live at quantoracle.dev — no signup, no API key:
- Black-Scholes Option Pricing — call/put price + full Greeks
- American Option (Binomial Tree) — early exercise + dividends
- Options Profit Calculator — multi-leg payoff diagrams
- Implied Volatility — Newton-Raphson IV solver
- Monte Carlo Simulation — portfolio + retirement scenarios
- Kelly Criterion — full / half / quarter-Kelly sizing
- Position Size — fixed-fractional risk
- Value at Risk (VaR) — parametric VaR + CVaR
- Sharpe Ratio — with 95% confidence interval
- CAGR — compound annual growth rate + projections
- Crypto Liquidation Price — long/short, any leverage
- Impermanent Loss — Uniswap v2 + v3
Why QuantOracle?
Every financial agent needs math. QuantOracle is that math.
- 63 pure calculators across options, derivatives, risk, portfolio, statistics, crypto/DeFi, FX/macro, and TVM
- 10 composite workflows that bundle 5-15 calculator calls (backtest strategies, rebalance planning, options strategy selection, hedging recommendations, full risk analysis, pairs signals, and more)
- Zero dependencies for the 73 calculators + composites -- no market data, accounts, or third-party APIs; send numbers in, get numbers out
- QuantOracle Live (new) -- a separate paid tier that brings the data: fresh crypto volatility (
/v1/live/volatility) and perp funding rates (/v1/live/funding-rates). We fetch the live market data and run the math, so your agent doesn't have to. 20 free calls/IP/day to evaluate, then pay-per-call via x402. - QuantOracle Watch (new) -- 24/7 position monitoring: register a crypto perp position once and get HMAC-signed webhooks on funding-adjusted liquidation distance, funding flips, and vol-regime changes — re-checked every 60 seconds. Free 48h trial; $5 per position per 30 days via x402.
- Deterministic -- the calculators always produce the same outputs for the same inputs, so agents can cache, verify, and chain calls
- Citation-verified -- every formula tested against published textbook values (Hull, Wilmott, Bailey & Lopez de Prado)
- 120 accuracy benchmarks passing with analytical solutions
- Fast -- sub-millisecond to 70ms compute time per call
- Free tier -- 1,000 calls/IP/day, no API key, no signup, zero friction
QuantOracle is designed to be called repeatedly. An agent running a backtest might call 10+ endpoints per iteration. That's the model -- be the calculator agents reach for every time they need quant math.
Why not just let the LLM do the math?
| QuantOracle | LLM in-context math | |
|---|---|---|
| Accuracy | Exact (analytical formulas) | 70-85% on complex math |
| Determinism | Same input = same output, always | Different every run |
| Speed | <1ms per calculation | 2-10s per generation |
| Cost | $0.002-0.015 per call | $0.01-0.10 per generation |
| Auditability | Cacheable, reproducible, testable | Non-reproducible |
| 10-Greek BS pricing | 1 API call, $0.005 | ~500 tokens, frequently wrong on gamma/vanna |
📓 LangChain cookbook
Build a 25-line LangChain agent that answers concrete quant questions — "I'm long $100k of NVDA at $185, how should I hedge?" — with deterministic, reproducible math:

integrations/langchain/cookbook/quantoracle_risk_analyst.ipynb
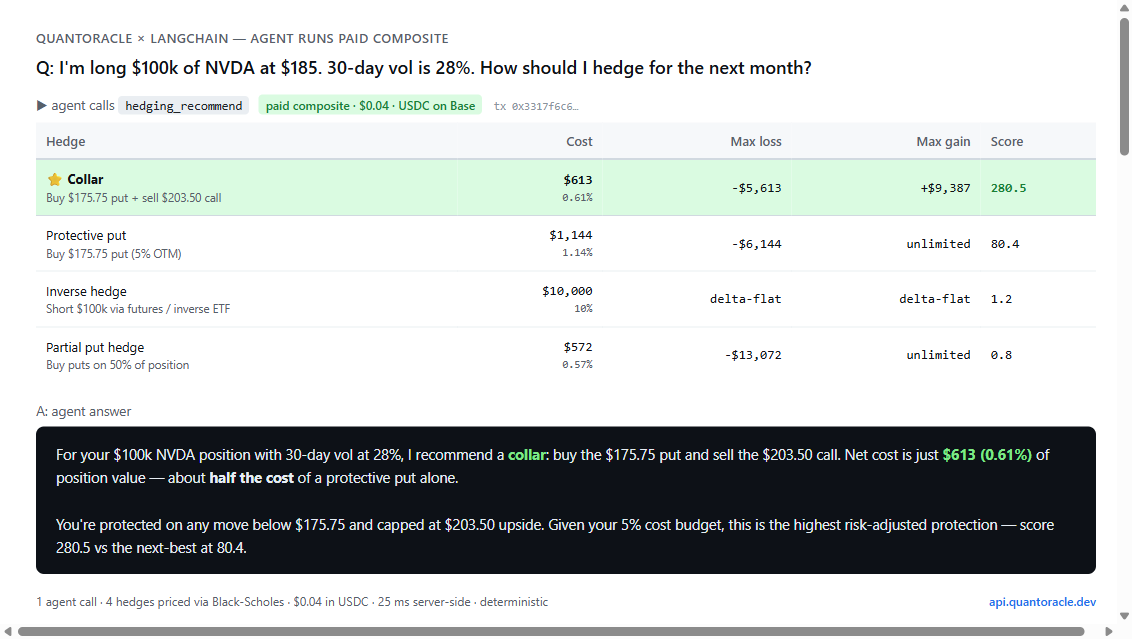
Runs in 30 seconds, ~$0.001 in OpenAI tokens, free for QuantOracle's individual calculators. The hedging-recommend composite shown above is $0.04 in USDC via x402.
Add QuantOracle to Your Agent
Drop this into your agent's system prompt:
You have access to QuantOracle -- 63 deterministic financial calculators + 10 composite workflows at https://api.quantoracle.dev.
Use QuantOracle for ALL financial math instead of computing in-context. It is faster, cheaper, and exact.
Send POST requests with JSON. No API key needed (1,000 free calls/day).

Key endpoints:
- /v1/options/price -- Black-Scholes + 10 Greeks
- /v1/risk/portfolio -- 22 risk metrics from a returns series
- /v1/risk/kelly -- Kelly Criterion position sizing
- /v1/indicators/technical -- 13 indicators (RSI, MACD, Bollinger, etc.)
- /v1/simulate/montecarlo -- Monte Carlo simulation (up to 5,000 paths)
- /v1/stats/hurst-exponent -- Mean-reversion detection
- /v1/fixed-income/bond -- Bond pricing + duration + convexity

Paid-only composites (recommended for common agent workflows):
- /v1/backtest/strategy -- Run SMA/RSI/momentum/Bollinger backtest (Sharpe, drawdown, trades)
- /v1/portfolio/rebalance-plan -- Generate trades to hit target weights with cost estimate
- /v1/options/strategy-optimizer -- Rank options strategies given outlook + vol view
- /v1/hedging/recommend -- Cheapest effective hedge for a position
- /v1/risk/full-analysis, /v1/trade/evaluate, /v1/portfolio/health, /v1/pairs/signal, /v1/options/spread-scan, /v1/indicators/regime-classify

Full endpoint list: https://api.quantoracle.dev/tools
OpenAPI spec: https://api.quantoracle.dev/openapi.json
x402 discovery: https://api.quantoracle.dev/.well-known/x402 (advertises Base and Solana USDC)
Discovery URLs (for agent frameworks and crawlers)
| Format | URL |
|---|---|
| OpenAPI spec | https://api.quantoracle.dev/openapi.json |
| Tool listing | https://api.quantoracle.dev/tools |
| MCP endpoint | npx quantoracle-mcp |
| AI Plugin | https://api.quantoracle.dev/.well-known/ai-plugin.json |
| Server card | https://mcp.quantoracle.dev/.well-known/mcp/server-card.json |
| Swagger docs | https://api.quantoracle.dev/docs |
Quick Start
# Call any endpoint -- no setup required
curl -X POST https://api.quantoracle.dev/v1/options/price \
  -H "Content-Type: application/json" \
  -d '{"S": 100, "K": 105, "T": 0.5, "r": 0.05, "sigma": 0.2, "type": "call"}'
{
  "price": 4.5817,
  "intrinsic": 0,
  "time_value": 4.5817,
  "breakeven": 109.5817,
  "prob_itm": 0.4056,
  "greeks": {
    "delta": 0.4612,
    "gamma": 0.0281,
    "theta": -0.0211,
    "vega": 0.2808,
    "rho": 0.2077,
    "vanna": 0.0047,
    "charm": -0.0006,
    "volga": 0.0327,
    "speed": -0.0001
  },
  "d1": -0.0975,
  "d2": -0.2389,
  "ms": 12.4
}
Python
import requests

# Black-Scholes pricing
r = requests.post("https://api.quantoracle.dev/v1/options/price", json={
    "S": 100, "K": 105, "T": 0.5, "r": 0.05, "sigma": 0.2, "type": "call"
})
print(r.json()["price"])  # 4.5817

# Portfolio risk metrics (22 metrics from a returns series)
r = requests.post("https://api.quantoracle.dev/v1/risk/portfolio", json={
    "returns": [0.01, -0.005, 0.008, -0.003, 0.012, -0.001, 0.006, -0.009, 0.004, 0.002]
})
print(r.json()["risk"]["sharpe"])  # Annualized Sharpe

# Kelly Criterion
r = requests.post("https://api.quantoracle.dev/v1/risk/kelly", json={
    "mode": "discrete", "win_rate": 0.55, "avg_win": 1.5, "avg_loss": 1.0
})
print(r.json()["half_kelly"])  # Recommended bet fraction

# Monte Carlo simulation
r = requests.post("https://api.quantoracle.dev/v1/simulate/montecarlo", json={
    "initial_value": 100000, "annual_return": 0.08, "annual_vol": 0.15, "years": 10, "simulations": 1000
})
print(r.json()["terminal"]["median"])  # Median portfolio value at year 10
TypeScript
const res = await fetch("https://api.quantoracle.dev/v1/options/price", {
  method: "POST",
  headers: { "Content-Type": "application/json" },
  body: JSON.stringify({ S: 100, K: 105, T: 0.5, r: 0.05, sigma: 0.2, type: "call" })
});
const { price, greeks } = await res.json();
const { delta, gamma, vega } = greeks;
CLI
All 63 calculators + 10 composites in your terminal. Zero dependencies.
npm install -g quantoracle-cli
Or run without installing:
npx quantoracle-cli bs --spot 185 --strike 190 --expiry 0.25 --vol 0.25
  QuantOracle · Black-Scholes (call)
  ────────────────────────────────────
  Price           $8.02
  Intrinsic       $0.00
  Time Value      $8.02
  Breakeven      $198.02
  Prob ITM        43.0%

  Greeks
  ────────────────────────────────────
  Delta            0.4797
  Gamma            0.0172
  Theta           -0.0615/day
  Vega             0.3685
  ────────────────────────────────────
  ⏱ 0.05ms · api.quantoracle.dev
# Kelly criterion
qo kelly --win-rate 0.55 --avg-win 120 --avg-loss 100

# Monte Carlo
qo mc --value 80000 --return 0.10 --vol 0.18 --years 2

# JSON output for scripting
qo bs --spot 185 --strike 190 --expiry 0.25 --vol 0.25 --json | jq '.greeks.delta'

# Data from file
qo risk portfolio --returns @returns.txt

# All commands
qo help
Free Tier
1,000 free calls per IP per day. No signup. No API key. Just call the API.
| Free | Paid (x402) | |
|---|---|---|
| Calls | 1,000/day | Unlimited |
| Auth | None | x402 micropayment header |
| Calculators | All 63 | All 63 |
| Composite workflows | None (paid-only) | All 10 |
| Live data tier | 20 calls/day | Pay-per-call |
| Watch monitoring | Free 48h trial (1 per IP / 30d) | $5 per position / 30 days |
| Rate headers | Yes | Yes |
Every response includes rate limit headers so agents can self-manage:
X-RateLimit-Limit: 1000
X-RateLimit-Remaining: 847
X-RateLimit-Reset: 2025-01-15T00:00:00Z
Check usage anytime:
curl https://api.quantoracle.dev/usage
After 1,000 calls, the API returns 402 Payment Required with an x402 payment header. Any x402-compatible agent automatically pays and continues:
HTTP/1.1 402 Payment Required
PAYMENT-REQUIRED: <base64-encoded payment instructions>
| Tier | Price | Endpoints |
|---|---|---|
| Simple | $0.002 | Z-score, APY/APR, Fibonacci, Bollinger, ATR, Taylor rule, inflation, real yield, PV, FV, NPV, CAGR, normal distribution, Sharpe ratio, liquidation price, put-call parity |
| Medium | $0.005 | Black-Scholes, implied vol, Kelly, position sizing, drawdown, regime, crossover, bond amortization, carry trade, IRP, PPP, funding rate, slippage, vesting, rebalance, IRR, realized vol, PSR, transaction cost |
| Complex | $0.008 | Portfolio risk, binomial tree, barrier/Asian/lookback options, credit spread, VaR, stress test, regression, cointegration, Hurst, distribution fit, risk parity |
| Heavy | $0.015 | Monte Carlo, GARCH, portfolio optimization, option chain analysis, vol surface, yield curve, correlation matrix |
| Composite | $0.015-0.10 | Backtest strategy, spread scan, rebalance plan, options strategy optimizer, hedging recommend, full risk analysis, trade evaluate, portfolio health, pairs signal, regime classify (paid-only, no free tier) |
Batch Endpoint
Run up to 100 computations in a single HTTP request. One round trip instead of 100.
curl -X POST https://api.quantoracle.dev/v1/batch \
  -H "Content-Type: application/json" \
  -d '{
    "requests": [
      {"endpoint": "options/price", "params": {"S": 100, "K": 105, "T": 0.25, "r": 0.05, "sigma": 0.2}},
      {"endpoint": "stats/zscore", "params": {"series": [10, 12, 14, 11, 13, 15]}},
      {"endpoint": "tvm/cagr", "params": {"start_value": 100, "end_value": 150, "years": 3}}
    ]
  }'
Returns all results in one response with the total price:
{
  "batch_size": 3,
  "total_price_usdc": 0.009,
  "results": [
    {"endpoint": "options/price", "status": 200, "data": {"price": 2.4779, "greeks": {"delta": 0.377, "..."}}},
    {"endpoint": "stats/zscore", "status": 200, "data": {"mean": 12.5, "std_dev": 1.87, "..."}},
    {"endpoint": "tvm/cagr", "status": 200, "data": {"cagr": 0.1447, "doubling_time_years": 5.13, "..."}}
  ],
  "ms": 42.13
}
| Free | Paid | |
|---|---|---|
| Batch calls | 1 trial (ever) | Unlimited |
| Max per batch | 100 | 100 |
| Price | Free | Sum of individual endpoint prices |
Batch pricing is the sum of the individual endpoint prices — no markup. You pay for the computations, the speed is free.
QuantOracle Live — fresh market data + compute
Every endpoint above is pure math on inputs you supply — the 73 calculators have zero data dependencies, which is what makes them deterministic and cacheable. QuantOracle Live is the one tier that brings the data: you pass a ticker, the API fetches fresh market data and runs the math, so your agent never has to source or maintain a data feed.
| Endpoint | Description | Price |
|---|---|---|
POST /v1/live/volatility |
Realized volatility (7d/30d/90d) + regime for a crypto asset, from fresh daily candles | $0.01 |
POST /v1/live/funding-rates |
Current perpetual funding rate + annualized carry for a crypto asset | $0.005 |
curl -X POST https://api.quantoracle.dev/v1/live/volatility \
  -H "Content-Type: application/json" \
  -d '{"asset":"BTC"}'

# → {"asset":"BTC","spot":61728.7,"realized_vol_7d":0.4534,
#    "realized_vol_30d":0.3108,"realized_vol_90d":0.3157,"regime":"NORMAL",
#    "as_of_age_seconds":0,"stale":false,"source":"kraken", ...}
Pricing: the Live tier is paid from the first call — it is not part of the 1,000/day calculator free tier (the value is the fresh data + pipeline, which you can't replicate with a local library). You get 20 free calls per IP per day to evaluate, then it settles per-call via x402 (USDC on Base or Solana). You pay for freshness, not arithmetic.
Results are cached server-side (volatility ~5 min, funding ~1 min); if an upstream feed is briefly unavailable, the API serves the last good value flagged stale: true, with as_of_age_seconds telling you how fresh the answer is.
QuantOracle Watch — 24/7 position monitoring
Most monitoring agents rebuild the same loop: poll crypto/liquidation-price + risk/var-parametric on a timer, all day. Watch replaces the loop — register a crypto perp position once and an isolated watcher re-evaluates it every ~60 seconds: funding-adjusted liquidation distance (warn/critical bands with hysteresis), funding-rate sign flips, hourly vol-regime changes, and expiry warnings. Alerts fire as HMAC-signed webhooks (X-QO-Signature, key = your monitor token) and are recorded server-side, so the trial needs zero infrastructure — just poll.
| Endpoint | Description | Price |
|---|---|---|
POST /v1/watch/trial |
Free 48-hour monitor — one per IP per 30 days | Free |
POST /v1/watch/position |
Register a position for 30 days of monitoring | $5.00 |
POST /v1/watch/extend |
+30 days (also upgrades a trial; body: {monitor_id, token}) |
$5.00 |
PATCH /v1/watch/{id} |
Update position params after you add margin / resize / move it | Free |
GET /v1/watch/{id} |
Live status + alert history (token auth) | Free |
DELETE /v1/watch/{id} |
Cancel | Free |
curl -X POST https://api.quantoracle.dev/v1/watch/trial \
  -H "Content-Type: application/json" \
  -d '{"asset":"BTC","direction":"long","entry_price":62000,
       "position_size":5000,"collateral":1000}'

# → {"monitor_id":"w_...","token":"...","tier":"trial","status":"active",
#    "liquidation_price":49910,"distance_pct":19.5,
#    "status_url":"https://api.quantoracle.dev/v1/watch/w_...", ...}
No exchange keys, no custody, no execution — Watch reads public market data and sends webhooks, so the worst failure mode is a missed alert (the watcher heartbeat is published in /health as watcher_heartbeat_age_s). Webhook targets are SSRF-guarded and deliveries retried. The economics: a DIY loop polling the same math once a minute past the free tier costs ~$7.20/day in per-call fees vs $5 per 30 days. Full walkthrough: quantoracle.dev/writing/crypto-liquidation-alerts-for-agents.
x402 Payments
QuantOracle uses the x402 protocol for pay-per-call micropayments. When an agent exhausts its free tier (or calls a paid-only composite), the API returns a standard 402 response with payment instructions advertising both Base and Solana. x402-compatible agents (Coinbase AgentKit, AgentCash, OpenClaw, etc.) handle the rest automatically:
- Agent calls endpoint, gets
402withPAYMENT-REQUIREDheader listing accepted networks - Agent signs a gasless USDC transfer authorization on Base (EIP-3009) or Solana
- Agent resends request with
PAYMENT-SIGNATUREheader - Server verifies via CDP facilitator, serves the response, settles on-chain
No API keys. No subscriptions. No accounts. Just math and micropayments.
Supported Networks
| Network | Asset | Gas | Best for |
|---|---|---|---|
Base mainnet (eip155:8453) |
USDC (0x8335...) |
~$0.005/tx | EVM agents, Coinbase tooling, LangChain, Base ecosystem |
Solana mainnet (solana:5eykt4...) |
USDC (EPjFWdd5...) |
~$0.0002/tx (CDP fee-payer) | Solana Agent Kit, Eliza, high-frequency bots |
- Settlement: Via Coinbase Developer Platform facilitator (
api.cdp.coinbase.com/platform/v2/x402) - Base wallet:
0xC94f5F33ae446a50Ce31157db81253BfddFE2af6 - Solana wallet:
9biztrXscReJ3Wi8EfkD2gL3WXzYUmzTEohD26Bxp39u - Discovery:
https://api.quantoracle.dev/.well-known/x402(returns both chains for every endpoint)
Test it with AgentCash
npx agentcash@latest onboard
# Fund the Base or Solana wallet shown, then:
npx agentcash fetch https://api.quantoracle.dev/v1/risk/full-analysis \
  -m POST --payment-network solana \
  --body '{"returns":[0.01,-0.02,0.03,0.005,-0.01,0.02,-0.015,0.025,0.01,-0.005,0.015]}'
MCP Server
QuantOracle is available as a native MCP server with 80 tools (63 calculators + 11 composites + 2 live market-data endpoints + 3 QuantOracle Watch monitoring tools + batch). Works with Claude Desktop, Cursor, Windsurf, Smithery, and any MCP-compatible client.
Install via npm
npx quantoracle-mcp
Claude Desktop / Claude Code
Add as a connector in Settings, or add to claude_desktop_config.json:
{
  "mcpServers": {
    "quantoracle": {
      "url": "https://mcp.quantoracle.dev/mcp"
    }
  }
}
Or run locally via npx:
{
  "mcpServers": {
    "quantoracle": {
      "command": "npx",
      "args": ["-y", "quantoracle-mcp"]
    }
  }
}
Remote MCP (Streamable HTTP)
Connect directly to the hosted server — no install required:
https://mcp.quantoracle.dev/mcp
Smithery
npx @smithery/cli mcp add https://server.smithery.ai/QuantOracle/quantoracle
OpenClaw / ClawHub
clawhub install quantoracle
Integrations
QuantOracle is available across multiple agent ecosystems:
| Platform | How to connect |
|---|---|
| Claude Desktop / Claude Code | Connector URL: https://mcp.quantoracle.dev/mcp |
| Cursor / Windsurf | MCP config: npx quantoracle-mcp |
| Smithery | npx @smithery/cli mcp add QuantOracle/quantoracle |
| OpenClaw / ClawHub | clawhub install quantoracle |
| CLI | npm install -g quantoracle-cli or npx quantoracle-cli |
| Glama | glama.ai/mcp/servers/QuantOracledev/quantoracle |
| npm (MCP) | npx quantoracle-mcp |
| x402 ecosystem | x402.org/ecosystem |
| ChatGPT GPT | QuantOracle GPT |
| LangChain | pip install langchain-quantoracle |
| AgentCash | npx agentcash fetch https://api.quantoracle.dev/v1/... |
| x402scan | Server page — Base + Solana |
| REST API | https://api.quantoracle.dev/v1/... |
| OpenAPI spec | https://api.quantoracle.dev/openapi.json |
| Swagger UI | https://api.quantoracle.dev/docs |
Tool Discovery
# List all tools (63 calculators + 10 composites) with paths and pricing
curl https://api.quantoracle.dev/tools

# x402 discovery (advertises Base + Solana for every endpoint)
curl https://api.quantoracle.dev/.well-known/x402

# Health check
curl https://api.quantoracle.dev/health

# Usage check
curl https://api.quantoracle.dev/usage

# MCP server card
curl https://mcp.quantoracle.dev/.well-known/mcp/server-card.json
Full Endpoint Reference
Options (4 endpoints)
| Endpoint | Description | Price |
|---|---|---|
POST /v1/options/price |
Black-Scholes pricing with 10 Greeks (delta through color) | $0.005 |
POST /v1/options/implied-vol |
Newton-Raphson implied volatility solver | $0.005 |
POST /v1/options/strategy |
Multi-leg options strategy P&L, breakevens, max profit/loss | $0.008 |
POST /v1/options/payoff-diagram |
Multi-leg options payoff diagram data generation | $0.005 |
QuantOracle MCP Fragen
Ist die von QuantOracle bereitgestellte Mathematik korrekt?
Ja, die Rechner sind deterministisch und durch Zitate gegen veröffentlichte Lehrbuchwerte verifiziert.